
How Manufacturing Businesses Can Control Rising Healthcare Costs
A practical guide to reviewing benefits spending, improving care access for shift workers, evaluating vendors, and measuring costs without overlooking employee needs.
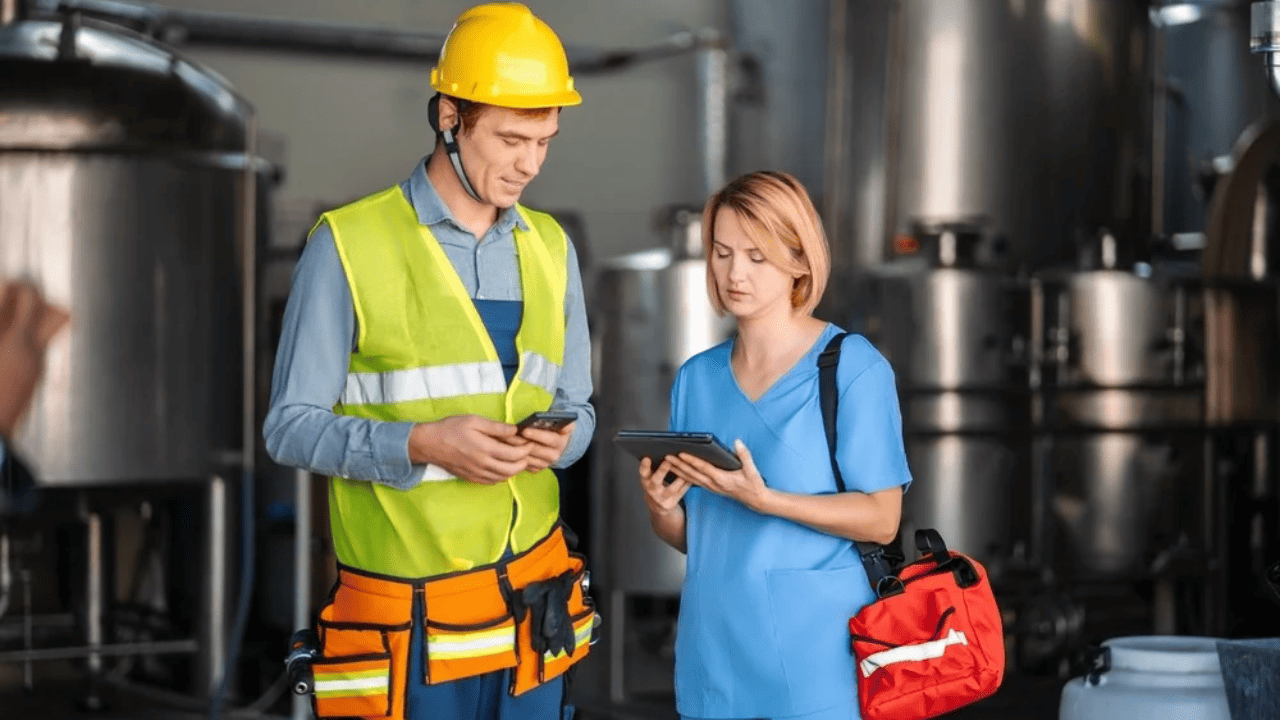
Manufacturing businesses can control rising healthcare costs by identifying spending drivers, reviewing benefits and vendor fees, and improving access to appropriate care for every shift. Compare proposals on total employer and employee costs, provider access, and service limitations. Coordinate workplace safety with medical support while tracking injury costs separately. Measure spending, access barriers, and employee feedback together. No strategy guarantees savings, and shifting costs to employees is not the same as reducing the cost of care.
Key takeaways
- Separate price increases, changes in service use, and access barriers before selecting a solution.
- Evaluate employer spending alongside employee contributions and costs when receiving care.
- Check that care hours, provider availability, and benefits support work for every shift.
- Keep workplace safety measures distinct from health plan spending while reviewing both.
- Require vendors to explain fees, exclusions, implementation needs, and savings assumptions.
- Evaluate SakeOf's advocacy and fair price review against specific employee needs, not as insurance or a promise of savings.
Controlling healthcare costs starts with knowing what is driving them. Before raising deductibles or switching vendors, manufacturing employers should separate price increases, enrollment changes, medical service use, and barriers that keep employees from getting appropriate care.
A plant running three shifts faces different access problems than an office operating during clinic hours. Physically demanding jobs also make workplace safety and timely medical support relevant. A useful cost strategy accounts for those realities without assuming that every program will produce savings.
1. Identify what is driving healthcare spending
Manufacturing employers balance benefits spending with production schedules, staffing levels, and operating budgets. Employees may work overtime, rotate shifts, commute from rural communities, or have limited flexibility to attend appointments. A benefit that looks accessible on paper may be difficult to use during an actual workweek.
Spending can also change for reasons unrelated to how well a benefits program is managed. Higher service prices, prescription expenses, enrollment changes, and a small number of expensive medical events can affect the total. For a smaller manufacturer, one major event can make annual spending especially difficult to interpret.
Separate three questions before choosing a response:
- Price: Is the business paying more for the same benefits or services?
- Use: Have the number, type, or complexity of medical services changed?
- Access: Are employees delaying appropriate care because of schedules, cost, or provider availability?
A price problem calls for a different review than a clinic access problem, even when both show up as higher spending.
2. Build a spending baseline before changing benefits
Ask your broker, administrator, or benefits vendors for the information available under your arrangement. Start with enrollment, employer contributions, employee contributions, renewal history, administrative fees, and benefit use. Where claims information is available, request aggregate reporting that protects employee privacy.
For a fully insured plan, premiums and renewal terms are central to the employer budget. For a self funded arrangement, paid claims, administrative charges, stop loss coverage, and funding requirements also need review. Do not compare these arrangements using only their most visible monthly charge.
Organize the baseline into practical categories:
- Medical and prescription spending, where available
- Employer and employee contributions by enrollment tier
- Enrollment changes, including dependent enrollment
- Administrative, consulting, and separate vendor fees
- Large medical events and recurring spending patterns, using aggregate information
- Employee reports of appointment, billing, or affordability problems
Compare spending per enrolled employee or member as well as total spending. A growing plant may spend more simply because it covers more people. Use consistent definitions and comparable time periods so enrollment changes do not look like changes in program performance.
Small manufacturers may not have detailed claims reports or enough data to support firm conclusions. In that case, combine financial records with provider directory checks, vendor service reports, and confidential employee feedback rather than treating a small data set as definitive.
3. Review benefit design, provider access, and employee costs together
A lower employer contribution does not necessarily mean healthcare became less expensive. It may mean employees now pay more through payroll deductions, deductibles, or other charges. Evaluate the combined effect before calling a proposed change a cost reduction.
Test each proposal against realistic employee situations: a machine operator managing recurring prescriptions, a parent seeking evening pediatric care, and an employee needing rehabilitation after surgery. Review what each person would pay, where they could receive care, and what approvals or restrictions might apply.
Check provider access near employees' homes, not just near the plant. Confirm that relevant primary care practices, hospitals, specialists, and pharmacies participate in the proposed arrangement. A directory listing alone does not establish that a practice is accepting new patients or offers workable appointment times.
Prescription reviews should consider the medications employees rely on, applicable restrictions, pharmacy access, and employee charges. Avoid making decisions based only on a vendor's headline discount or an example of one inexpensive drug.
Benefit design involves tradeoffs. A narrower network may offer attractive pricing but less provider choice. Lower payroll deductions may come with greater costs when care is needed. Ask a qualified benefits professional to explain those tradeoffs and review the proposed arrangement before making changes.
4. Make healthcare usable for every shift
Healthcare benefits for shift workers need to work outside standard office hours. A night shift employee may finish work when a clinic opens but still need sleep before the next shift. Rotating schedules can also make recurring appointments difficult to keep.
Map available services against each shift's actual schedule. Ask employees where they encounter problems, such as transportation, appointment availability, difficulty reaching a benefits representative, or uncertainty about where to seek care. Offer feedback channels that do not require employees to disclose diagnoses to supervisors.
- Check evening and weekend access: Verify local clinic hours and appointment availability rather than assuming extended hours exist.
- Evaluate virtual care: Review service hours, clinical scope, costs, language support, and instructions for situations requiring in person care.
- Review scheduling practices: Explore appointment flexibility that fits production needs without making employees unnecessarily postpone care.
- Repeat benefits communication: Provide sessions and materials for every shift, with clear contact information for questions.
- Support preventive care: Explain available services and how employees can schedule them, without promising that participation will lower future spending.
Adding a virtual service will not solve an access problem if employees cannot use their phones privately or the service is unavailable after their shift. Onsite services may be useful for some facilities, but staffing, privacy, clinical scope, and likely use should be evaluated before committing to a contract.
5. Connect workplace safety with appropriate medical support
Safety and benefits teams should coordinate, but workplace injury costs and general employee healthcare spending are not interchangeable. Occupational injuries may involve different coverage, reporting, and administrative processes. Keep those distinctions clear when measuring results.
Review tasks involving repetitive motion, awkward reaches, heavy handling, vibration, or prolonged standing with qualified safety professionals. Equipment maintenance, ergonomic assessments, task design, and supervisor training can address workplace hazards. Safety programs are not substitutes for medical care and should never discourage injury reporting.
Make the process for reporting discomfort or an injury clear across all shifts. Employees should know whom to contact and how to obtain appropriate evaluation. Supervisors should support that process rather than attempt to diagnose symptoms or determine treatment.
Where appropriate, coordinate job accommodations or return to work planning with qualified professionals. Keep medical information private and give managers only the information needed for their role. Track safety outcomes separately from health plan spending, then look for patterns without assuming one caused the other.
When budgeting for workplace injury prevention, include training time, equipment, maintenance, and implementation effort. Evaluate the program's safety purpose directly rather than requiring an unsupported promise of lower medical claims.
6. Compare vendors using the same questions
Require each vendor to describe its services, limitations, fees, and measurement methods in writing. A proposal should explain not only the projected financial result but also what employees must do differently to receive care.
- What costs are included, and which charges are separate?
- What assumptions support any projected savings?
- Do projections account for implementation costs and overlap with existing services?
- Which providers, services, medications, or situations are excluded?
- What support is available to each shift and in relevant languages?
- How are service problems, privacy, reporting, and contract termination handled?
- How will employees transition if providers or benefit rules change?
Insurance and membership programs should not be treated as interchangeable. Insurance proposals should be evaluated on their coverage terms, employee costs, and access. Membership proposals need a separate review of what they provide and what they do not promise.
Where SakeOf may fit in the review
SakeOf is not insurance. It is a membership program combining healthcare advocacy, fair price review, direct service and discount benefits when selected, and voluntary member to member community funding for eligible medical expenses.
For a manufacturer whose employees report billing confusion or difficulty navigating medical expenses, SakeOf's healthcare advocacy and fair price review are specific services to evaluate. They address a different need from changing an insurance deductible or provider network. If SakeOf needs to speak with a provider on a member's behalf about billing or eligibility for sharing, a release form may be needed.
Compare the membership cost, selected benefits, current terms, and any overlap with existing services against the problems employees actually report. Ask whether service availability fits your shifts rather than assuming it does. Potential community sharing is not guaranteed payment, and membership should not be assumed to replace an insurance policy or reduce employer premiums.
SakeOf itself may be used alongside other healthcare arrangements, but individual third party benefits may have coordination restrictions. Do not assume that a prescription or telehealth benefit can be combined with an insurance claim unless current vendor terms confirm it.
7. Track spending, access, and employee experience
Choose a manageable dashboard before launching changes. Record the starting point, who owns each measure, and when the team will review results. Financial reporting alone will not show whether employees are having trouble getting care.
- Budget: Track total employer spending and spending per enrolled employee or member.
- Employee costs: Review payroll contributions and available aggregate information about costs when receiving care.
- Access: Monitor appointment barriers, provider availability, and service hours.
- Service quality: Review billing complaints, support response times, and unresolved issues.
- Workplace safety: Track hazards, reported injuries, and corrective actions separately.
- Workforce feedback: Gather confidential input across shifts, locations, and job roles.
Review operational problems regularly and financial results over a period long enough to account for enrollment changes, claims timing, and unusual medical events. Lower spending is not automatically a success if employees report delaying necessary treatment. Higher spending does not automatically mean a useful program failed.
Start with a documented baseline and a few specific problems to solve. Choose changes that address those problems, explain the tradeoffs to employees, and compare results against the baseline before expanding or renewing a program.
Common questions
What commonly drives healthcare spending for manufacturing employers?
Drivers can include higher service prices, prescription expenses, enrollment changes, and expensive medical events. Shift schedules and limited local provider availability can also make appropriate care harder to obtain. Review actual spending and employee access problems rather than assuming the cause.
How can a small manufacturer review benefits costs without detailed claims data?
Start with premiums, employer contributions, enrollment, renewal history, and all separate fees. Compare consistent periods and calculate spending per enrolled employee or member. Supplement those records with provider access checks, vendor service reports, and confidential employee feedback.
How can manufacturers improve healthcare access for shift workers?
Check clinic hours, appointment availability, and benefits support against each shift's schedule. Evaluate virtual care hours and limitations, provide benefits education across shifts, and explore appointment flexibility. Ask employees about barriers without requiring them to share diagnoses with supervisors.
How can employers address healthcare costs without reducing access?
Investigate administrative fees, provider pricing, duplicate services, and practical access barriers before shifting more costs to employees. Evaluate proposed changes using realistic employee care needs. Monitor appointment access and reports of delayed care alongside financial results.
Can workplace safety programs guarantee lower healthcare costs?
No. Safety efforts should address hazards and support appropriate injury reporting and medical evaluation. They are not substitutes for medical care, and any effect on spending needs to be measured rather than assumed. Track occupational injury costs separately from general health plan spending.
What should manufacturers ask benefits vendors about projected savings?
Ask which assumptions support the projection, what fees and implementation costs are included, and whether projected savings overlap with existing programs. Request written details about exclusions, provider access, employee costs, service hours, reporting, and transition support.
How might SakeOf help employees with healthcare expense concerns?
SakeOf offers healthcare advocacy and fair price review, which employers can evaluate when employees report billing confusion or difficulty navigating medical expenses. Selected direct service and discount benefits may also be relevant, subject to current terms. SakeOf is not insurance, and voluntary community funding for eligible expenses does not guarantee payment or savings.
Ready to keep exploring?
Use SakeOf tools and program information to compare your next healthcare decision with clearer cost context.
Build a Smarter Healthcare CostSakeOf Healthcare & Pregnancy Estimator
See real costs for major medical events – and how SakeOf protects your family from financially devastating bills.
Estimates are rough ranges for marketing purposes only and may vary by provider and location.
See how quickly a hospital bill adds up.
Take a quick walk through our interactive hospital experience.
Play the hospital gameKeep reading
Related guides and answers from SakeOf Insights.
How to Get a Written Estimate Before Care
Learn who to contact, what details to provide, and how to check a written medical estimate before a planned appointment, test, or procedure.
Rising Health Insurance Costs: Why They Rise and What to Review
A higher premium is only one reason healthcare spending can rise. Learn how to review a renewal, compare yearly plan costs, and check the tradeoffs before changing coverage.
Why Can Blue Collar Industries Face Higher Medical Costs, and What Can Help?
Physical demands, injuries, access to care, and workforce differences can affect medical spending. Here is how employers and workers can address costs while keeping workplace injury expenses separate
How to Find an Independent Imaging Center Before You Book
Find local imaging options, verify the exact test and order requirements, and compare credentials, scheduling, and written estimates before booking.